A zero depreciation claim can reduce one of the biggest deductions applied to car repair settlements, but it does not mean every repair expense disappears. Car owners may still need to pay certain amounts depending on deductibles, policy terms, approved repair work, and add-on coverage.
Understanding these possible out-of-pocket costs before a claim helps avoid confusion at the garage. It also makes it easier to read the claim estimate and know which expenses remain your responsibility after assessment beforehand.
What You Pay in a Zero Depreciation Claim
Zero depreciation cover generally reduces the depreciation deduction applied to eligible replaced parts during an admissible partial-loss claim, subject to the policy terms. You can buy car insurance online with suitable add-ons, including zero depreciation cover where available, but the add-on does not remove every expense associated with a claim.
- You may still pay applicable deductibles.
- Non-covered items can remain payable by you.
- Repairs outside the approved scope may be charged separately.
- The final amount depends on policy terms and claim assessment.
- Policy conditions still govern settlement.
Compulsory Deductible You Still Have to Pay
A compulsory deductible is the portion of an admissible own-damage claim that the policyholder must bear. Zero depreciation cover does not normally remove this requirement because it addresses depreciation on eligible parts, not the deductible specified under the motor policy.
- The deductible applies according to the policy terms.
- It is adjusted while settling the eligible claim.
- Check your policy schedule for the amount.
- The payable amount can differ according to the insured vehicle and policy structure.
- It remains your responsibility.
Voluntary Deductible, if You Selected One
A voluntary deductible is an additional amount you agree to bear when purchasing the policy, usually in exchange for a reduction in the own-damage premium. When selected, it generally applies in addition to the compulsory deductible and can increase what you pay during a claim.
- Confirm whether you opted for this deductible.
- Review the amount shown in your policy schedule.
- It may apply even with zero depreciation cover.
- Consider its effect on out-of-pocket expenses.
- Understand this trade-off before selecting it.
Consumables and Other Non-covered Expenses
Repair work often uses items that are consumed during servicing rather than fitted as lasting replacement parts. Depending on the policy and add-ons chosen, items such as lubricants, coolants, fasteners, filters, sealants, or similar workshop materials may not fall within zero depreciation protection itself.
- Consumables may require a separate add-on.
- Garage supplies can appear as non-payable items.
- Some parts may have policy treatment.
- Always check the add-on wording before assuming every repair item is covered.
- Coverage varies between policy structures.
Costs above the Approved Claim Amount
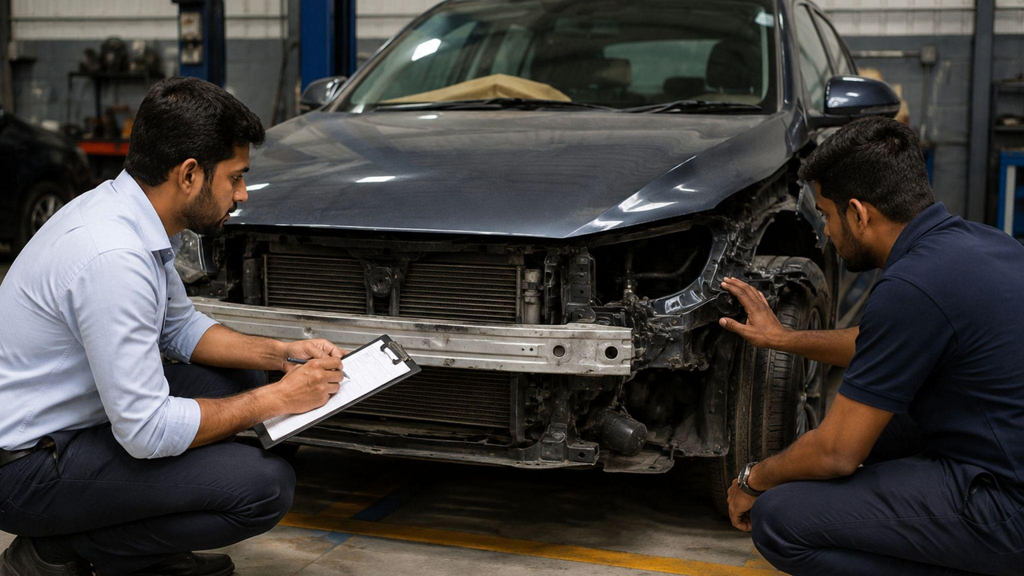
The garage estimate and the insurer-approved claim amount may not always be identical. The insurer assesses whether the reported damage is admissible under the policy and whether the proposed repair or replacement is connected to the insured event. Any difference may become your responsibility.
- Unapproved repairs can increase your payable share.
- Additional work requested separately may not be reimbursed.
- Claim approval follows assessment and policy conditions.
- Ask for a break-up before authorising extra repair work.
- Keep documents for disputed items.
Expenses Caused by Policy Exclusions
Zero depreciation cover works within the terms of the underlying motor policy. It does not convert an otherwise inadmissible loss into a payable claim. If damage arises from a situation excluded under the policy, the expense may remain with the car owner.
- Exclusions continue to apply to the claim.
- Add-on benefits remain subject to conditions.
- Unrelated damage may be kept outside the settlement.
- Reading the policy wording helps distinguish covered damage from non-admissible repair work.
- Clarify doubtful items before authorisation.
Repair Costs beyond the Coverage Limit
Insurance pays according to the scope and limits stated in the policy and applicable add-ons. Zero depreciation mainly changes how depreciation is treated on eligible parts; it does not automatically increase every policy limit. If a covered expense is subject to a stated limit, the excess can fall on you.
- Check limits mentioned in the policy schedule.
- Review limits attached to optional covers.
- Confirm whether a repair has a specific cap.
- Ask the insurer how the limit affects settlement clearly.
Your Final Out-of-Pocket Cost
Your final payment is best understood as the portion of the repair bill that remains after the insurer settles the admissible amount. With zero depreciation cover, depreciation on eligible parts may be removed, but other policy-based deductions or non-payable expenses can still apply.
- Add applicable compulsory and voluntary deductibles.
- Include non-covered consumables or repair items.
- Account for work beyond the approved claim.
- Check any relevant policy limits.
- Review the settlement summary before paying the garage.
- Clarify unfamiliar deductions before payment.
Conclusion
Zero depreciation cover can make an own-damage claim easier on your wallet by reducing depreciation-related deductions on eligible parts. Still, it should not be treated as a promise of a completely cash-free repair. Deductibles, consumables, non-admissible items, policy limits, and unapproved work may still affect what you pay. A practical approach is to read the policy schedule, add-on wording, and claim estimate together. That gives you a clearer picture of your share before repairs are completed and settlement is finalised.